ADU Financing Strategy
Digital HELOC for ADU Financing
A streamlined Digital HELOC can provide ADU funds quickly for qualified homeowners who already have enough current equity, often without replacing an existing first mortgage.
What a Digital HELOC is
A Digital HELOC is a home equity line of credit that uses a streamlined online application and verification process. For homeowners who already have sufficient current equity, it can be a faster, simpler way to access funds than a traditional equity loan that requires extensive in-person paperwork.
Like other HELOCs, it is secured by the borrower's home, and repayment obligations apply according to the loan documents.
Why speed and convenience can matter
ADU projects often move on tight timelines. Contractors, permits, and material availability can all create pressure to access funds quickly. A streamlined digital process can reduce friction for qualified borrowers who have the equity to support the line of credit.
“5-Day” describes a streamlined process that may be available for certain qualified borrowers and eligible properties. It is not a guarantee of closing or funding within five days. Actual timing depends on borrower responsiveness, documentation, verification, property information, valuation requirements, lender guidelines, underwriting, holidays, and third-party services.
Second-lien structure
A Digital HELOC is typically structured as a second lien. That means qualified homeowners can keep their existing first mortgage and its rate in place, adding a separate equity line secured by the property rather than refinancing the whole loan.
This can be attractive when you have a favorable first mortgage rate you do not want to give up. The HELOC carries its own terms, draw period, and repayment obligations.
General eligibility considerations
Eligibility generally depends on sufficient current equity, credit, income, debt-to-income ratio, and property eligibility. Because a Digital HELOC relies on current rather than future value, it tends to fit homeowners who already have the equity needed for their ADU project.
If current equity is limited, a Future Value HELOC may be a better fit. Not all applicants or properties will qualify.
Funding process
The process typically starts with an online application, followed by identity and income verification, property information, and valuation. For eligible transactions, funds may be available without the staged draws and inspections common in construction loans.
Actual timing varies, and no specific closing timeframe is guaranteed.
Potential ADU use cases
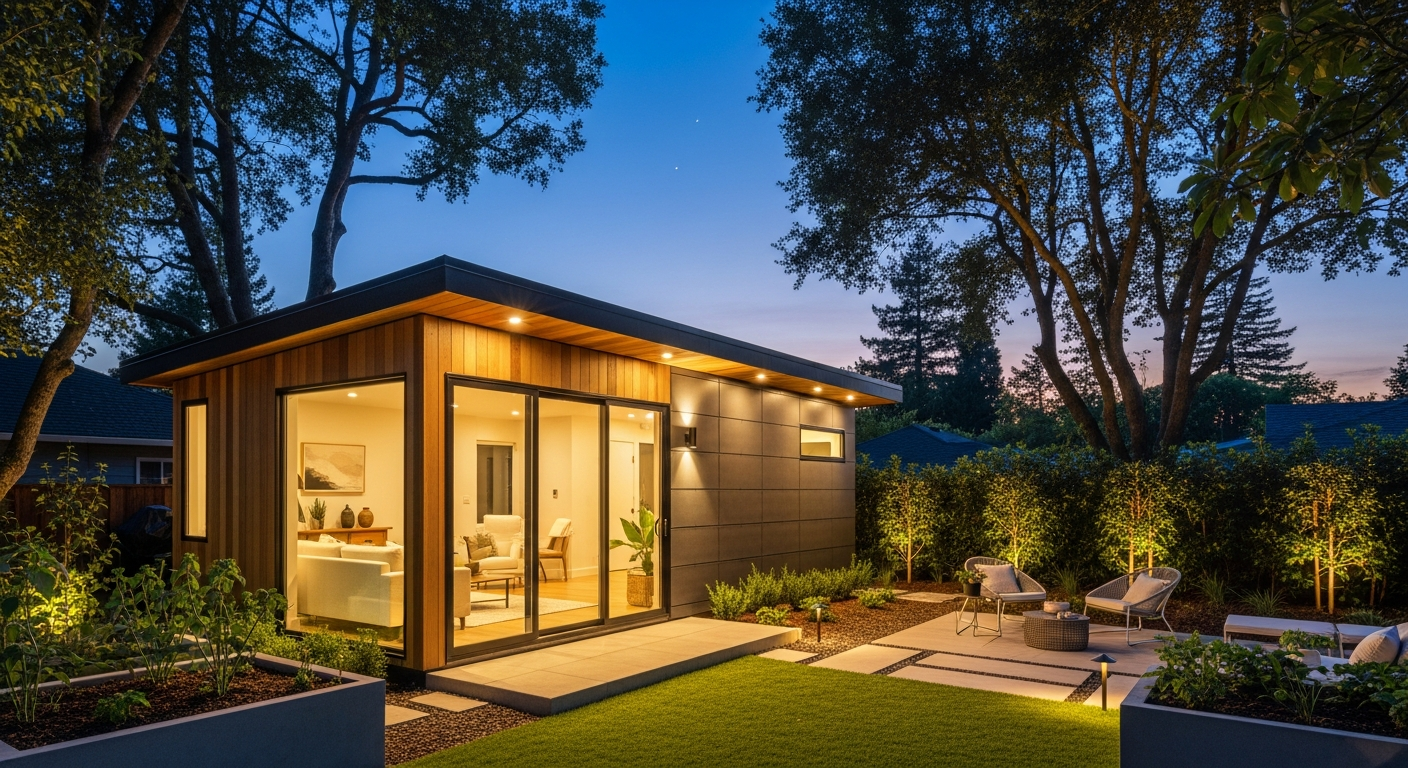
Qualified homeowners may use Digital HELOC funds toward a range of ADU-related goals, including detached ADUs, garage conversions, and modular ADU projects. Funds may also support related improvements that accompany the ADU, depending on the program and property.
Frequently Asked Questions
Related ADU financing options
Ready to explore your ADU financing options?
Contact Jim Park at Park Place Lending to review the strategy that fits your equity, property, and goals.
Reviewed by Jim Park, Mortgage Loan Originator, NMLS 2012003. Updated September 2026. This page is for informational purposes only and is not a commitment to lend.