Location Guide
ADU Financing in California
California homeowners have several equity-based ways to fund an ADU. This guide covers the financing strategies Park Place Lending helps qualified California borrowers evaluate.
California homeowner ADU financing considerations
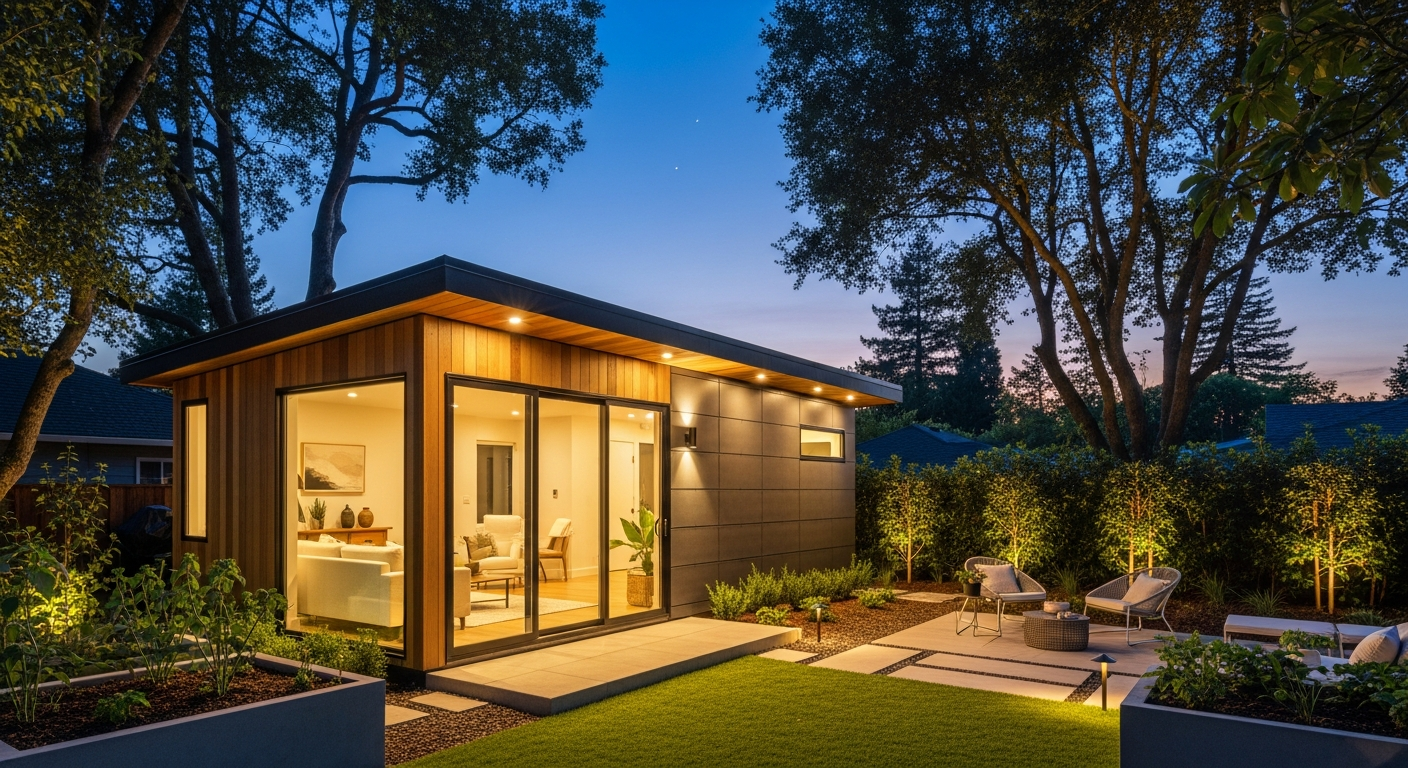
California has been a national leader in ADU-friendly regulations, and many homeowners are exploring accessory dwelling units for rental income, multigenerational living, or added property value. Financing is often the next question after deciding to build.
Park Place Lending & Investments Inc. serves qualified homeowners in California. Founder Jim Park, NMLS 2012003, specializes in ADU and home equity financing strategies tailored to each borrower's equity and goals.
Using equity
For California homeowners with built-up equity, a home equity approach is often the most cost-effective way to fund an ADU. Options include HELOCs, future-value financing, and home equity alternatives, many of which can be structured as a second lien to preserve an existing first mortgage.
Future value
A Future Value Renovation HELOC can be especially relevant in California, where completed ADUs may add meaningful value. By considering projected after-renovated value, qualified borrowers may access more equity than a standard HELOC would allow.
Projected value does not guarantee approval or a specific credit limit, and eligibility depends on valuation and underwriting.
HELOC options
A Digital HELOC offers a streamlined online process for qualified California homeowners who already have sufficient current equity. It is typically a second-lien product, so you can keep your existing first mortgage in place.
Modular ADUs
Modular construction is increasingly popular in California for its speed and predictability. Financing a modular ADU can involve factory deposits and construction timing that equity-based financing can help manage.
General financing process
The process typically begins with a conversation about your California property, equity, and ADU goals. From there, qualification, valuation, and documentation are completed. Some programs may not require completed building permits before closing, though California local permits and approvals are still required before construction where applicable.
Actual timing depends on borrower responsiveness, documentation, valuation, lender requirements, and underwriting. Not all applicants or properties will qualify.
A note on zoning and permits
California ADU rules vary by city and county, and local zoning, permits, and approvals are required before construction. This page does not provide legal or zoning advice; homeowners should confirm requirements with their local jurisdiction and qualified professionals.
Frequently Asked Questions
Related ADU financing options
Ready to explore your ADU financing options?
Contact Jim Park at Park Place Lending to review the strategy that fits your equity, property, and goals.
Reviewed by Jim Park, Mortgage Loan Originator, NMLS 2012003. Updated September 2026. This page is for informational purposes only and is not a commitment to lend.